English
 Tiếng Việt
NEW TAX REGULATIONS FOR FREELANCERS WHO DO NOT REGISTER AS BUSINESSES
Freelance work, project-based work, and online services are becoming increasingly common. However, not being registered as a business does not automatically mean that the income earned is exempt from tax. This is an important point for freelancers to keep in mind following the effective date of Decree No. 253/2026/ND-CP on July 1, 2026.
1. What do the new regulations provide?
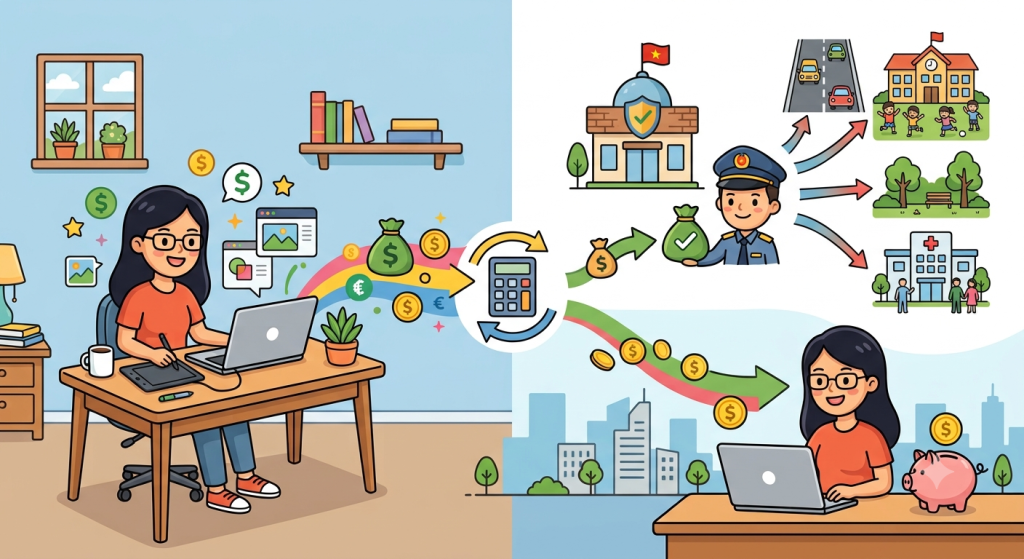
Decree No. 253/2026/ND-CP provides that remuneration received by an individual for providing services, where the individual has neither registered a business nor registered for tax purposes for business activities, is classified as employment income subject to personal income tax (PIT).
This may apply to a wide range of common freelance activities, including content writing, graphic design, software development, translation, consulting, teaching, videography, photography, and other project-based work.
The key point is that tax obligations are determined based on the nature and source of the income, rather than solely on whether the individual has registered a business.
2. Who should pay particular attention?
The regulation primarily affects individuals who regularly receive income from providing services while operating as individuals without registering a business or registering for tax purposes in relation to their business activities.
In addition to income recipients, businesses and organizations engaging freelancers should also pay attention to their tax withholding obligations where required by law.
In particular, individuals with multiple sources of income or those receiving payments from foreign clients or organizations should proactively review their tax obligations. They should not assume that payments made directly to a personal bank account are automatically outside the scope of tax administration.
3. What is the significance of the new regulation?
The regulation helps address gaps in tax administration arising from the growth of the freelance and digital economies. As more people earn income through project-based work, online platforms, and personal services, determining tax obligations based on actual income generated can help ensure greater fairness among individuals engaged in similar income-generating activities.
At the same time, the regulation places greater emphasis on transparency for freelancers: not registering a business does not mean that the individual is not required to pay tax.
4. What should freelancers do?
Freelancers should take proactive steps to:
– Keep track of and maintain records of income earned from providing services;
– Retain contracts, agreements, invoices, payment records, and other relevant documents;
– Check whether tax has already been withheld by the payer;
– If freelance activities are conducted regularly and generate significant income, consider registering under an appropriate business structure;
– If receiving income from multiple sources or from foreign clients, carefully review applicable tax filing and tax finalization obligations.
In summary, the new regulations do not mean that all freelancers are subject to the same amount or rate of tax. The specific tax obligations depend on factors such as the nature of the income, the status of the income recipient, where the income arises, and the method of payment.
Therefore, instead of focusing solely on whether a business has been registered, freelancers should focus on the more important legal question: How is their income classified under applicable law, and what tax obligations arise from that classification?