English
 Tiếng Việt
REVENUE THRESHOLDS AND TAX OBLIGATIONS FOR INDIVIDUALS SELLING GOODS ONLINE FROM 2026
The development of e-commerce and social media platforms has made online sales increasingly common. Accordingly, the determination of revenue and tax obligations applicable to individuals conducting business on Facebook, TikTok, Shopee, Lazada, TikTok Shop, and other platforms has become a matter of growing interest.
From 2026, the tax policies applicable to business households and individuals conducting business have undergone several notable changes, including an adjustment to the revenue threshold used as a basis for determining tax obligations.
Below are some key points that individuals selling goods online should take note of.
I. Revenue Threshold for Determining Tax Obligations
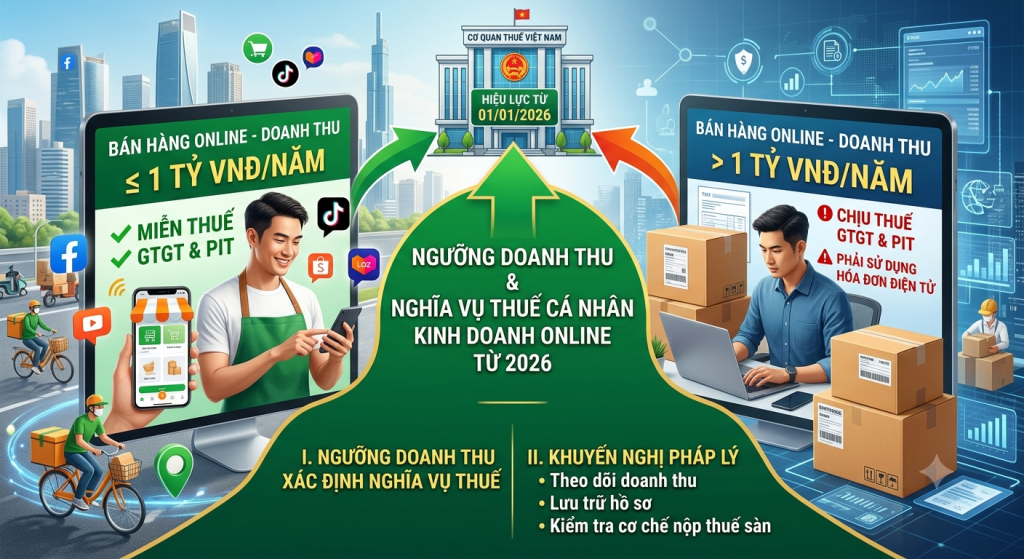
Under Decree No. 68/2026/ND-CP dated 5 March 2026, as amended and supplemented by Decree No. 141/2026/ND-CP dated 29 April 2026, tax policies applicable to business households and individuals conducting business are determined based on revenue. Notably, the revenue threshold for exemption from Value Added Tax (VAT) and Personal Income Tax (PIT) has been increased from VND 500 million per year to VND 1 billion per year. Decree No. 141/2026/ND-CP took effect on 1 January 2026.
Accordingly, individuals conducting business with annual revenue of VND 1 billion or less are not subject to VAT and are not required to pay PIT. Where annual revenue exceeds VND 1 billion, the individual is subject to VAT and PIT in accordance with applicable regulations.
For individuals selling goods online, this revenue threshold applies to actual business activities, including business activities conducted through e-commerce platforms. Therefore, individuals should monitor and fully determine the revenue generated from their business activities in order to accurately determine their tax obligations.
The current regulations have been consolidated in Consolidated Document No. 25/2026/VBHN-ND-BTC dated 13 August 2026 on tax policies and tax administration applicable to business households and individuals conducting business.
II. Legal Recommendations
The increase in the tax-exempt revenue threshold from VND 500 million to VND 1 billion per year creates more favorable conditions for small-scale business households and individuals conducting business. However, alongside the development of e-commerce, individuals selling goods online need to proactively monitor their revenue and determine the appropriate method for fulfilling their tax obligations. To ensure compliance with current regulations, individuals conducting business should take note of the following:
1. For individuals selling goods online:
- Monitor and consolidate revenue: Individuals should monitor revenue generated from all sales channels, including e-commerce platforms, social media, websites, and other online platforms, to determine whether their annual revenue exceeds VND 1 billion.
- Maintain records and supporting documents: Individuals should retain order information, transaction histories, bank statements, and other relevant supporting documents as a basis for determining revenue and providing explanations where necessary.
- Review tax obligations when exceeding the threshold: Where annual revenue exceeds VND 1 billion, individuals must fulfill their VAT, PIT, and other relevant tax obligations in accordance with the tax calculation method applicable to their business activities.
- Check the tax payment mechanism through e-commerce platforms: For e-commerce platforms that provide online ordering and payment functions, individuals should check whether the platform is responsible for tax withholding, declaration, and payment on their behalf. Where this mechanism does not apply, individuals are responsible for fulfilling their own tax obligations in accordance with applicable regulations.
2. For e-invoices and information provision:
- Proactively review e-invoice obligations: Individuals with annual revenue exceeding VND 1 billion are required to use e-invoices in accordance with applicable regulations. Individuals with annual revenue of VND 1 billion or less may register to use e-invoices when necessary and provided that the relevant conditions are satisfied.
- Provide accurate information: Individuals conducting business on e-commerce platforms should provide complete and accurate tax identification numbers, personal identification numbers, or other identification information as required by the platform and the tax authority.
The increase of the revenue threshold to VND 1 billion per year helps reduce the tax burden on small-scale business individuals, while also imposing greater requirements on revenue management, recording, and monitoring. Therefore, individuals selling goods online should proactively monitor their revenue and review the methods of tax declaration and payment, as well as e-invoice requirements, to ensure that they are appropriate to the scale of their business.