 English
 Tiếng Việt
NEW DRAFT RESOLUTION: TAX RELIEF MEASURESAND PENALTY AMNESTY FOR INACTIVEENTERPRISES
The Government is currently seeking public feedback on the Draft Resolution establishing specific policies to remove difficulties for taxpayers in complying with tax management laws, meeting urgent requirements for Exchange of Information on Request (EOIR). This is a critical step aimed at completely resolving long-standing issues for enterprises and household businesses that have suspended operations without completing tax identification number (TIN) deactivation procedures, while simultaneously fulfilling international commitments on tax transparency.
- Scope of Eligible Entities
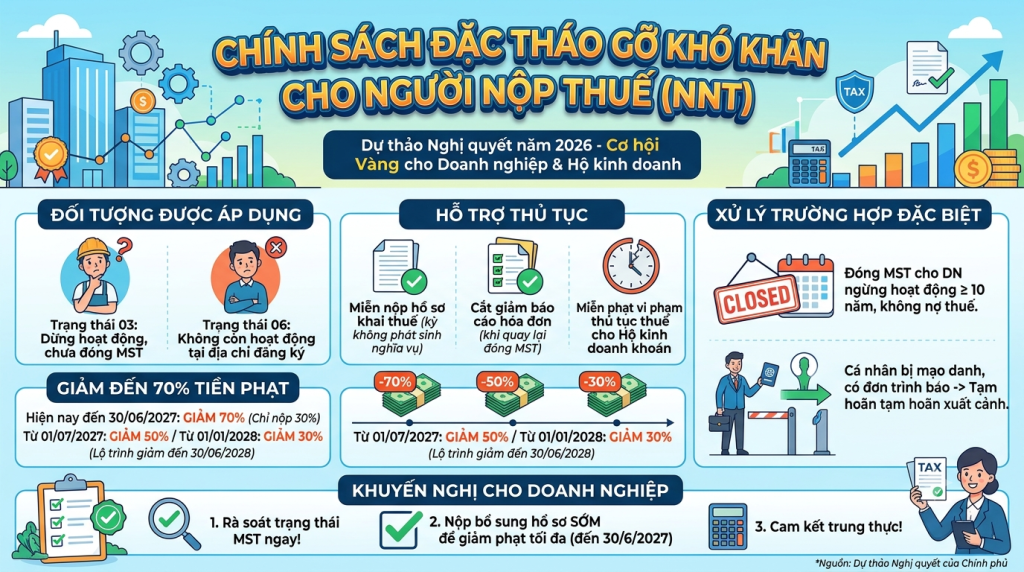
These policies directly target two groups of taxpayers experiencing status irregularities as of the effective date of the Resolution:
- Status 03: Taxpayers who have suspended business operations but have not completed procedures to deactivate their TIN.
- Status 06: Taxpayers no longer operating at their registered address as determined by tax authorities.
- Relaxation of Tax Declaration and E-Invoicing Filing Requirements
The draft resolution introduces significant administrative simplifications:
- Exemption from tax declarations: Eligible taxpayers are not required to submit tax returns for tax periods where no tax liabilities arise during the period of inactivity at their registered address.
- Revoked business licenses: Taxpayers whose Enterprise Registration Certificate or Business Registration Certificate has been revoked are exempt from tax declarations during the revocation period (except for tax finalization dossiers up to the revocation date).
- E-invoice report exemption: Taxpayers are exempt from preparing and submitting invoice reports/notices upon resuming procedures to deactivate their TIN until Decree No. 123/2020/ND-CP officially takes effect.
- Commitment requirement: Taxpayers must submit all outstanding tax returns for periods prior to inactivity and assume legal liability regarding the accuracy of periods committed as having no tax liability.
- Roadmap for Up to 70% Reduction in Administrative Fines
For administrative violations regarding late submission of tax declarations (under Decree No. 125/2020/ND-CP), taxpayers who submit all overdue returns will benefit from reduced fine rates based on the following timeline:
|
Submission Period of Overdue Tax Returns |
Applicable Fine Rate |
|
From Resolution effective date to June 30, 2027 |
30% of standard fine (70% reduction) |
|
From July 01, 2027 to December 31, 2027 |
50% of standard fine (50% reduction) |
|
From January 01, 2028 to June 30, 2028 |
70% of standard fine (30% reduction) |
- For household and individual businesses: Lump-sum taxpayers are fully exempt from procedural tax penalties. Declaration-based household businesses pay only 15% of standard fines (50% of the 30% rate) from the effective date through June 30, 2028.
- Important note: Fine reductions do NOT apply to acts exhibiting signs of tax evasion, fraud, illegal invoice usage, or cases currently under audit, investigation, prosecution, or trial.
- Special Provisions for Long-Term Inactive Businesses and Identity Theft Victims
- TIN deactivation for businesses inactive for ≥ 10 years: Enterprises/taxpayers inactive or absent from registered addresses for 10 consecutive years or more (as of the Resolution’s effective date) with no tax arrears and no active violations may be granted streamlined TIN deactivation. Tax authorities will publicly post business information for 30 days prior to finalizing deactivation.
- Temporary suspension of exit bans for identity theft victims: Individuals whose identity details were fraudulently used to register businesses will temporarily NOT be subject to travel/exit bans, provided they have filed formal complaints with police and relevant tax/business registration authorities while investigations are ongoing.
- Strategic Recommendations for Businesses
Review TIN Status Immediately: Proactively verify your company’s operational status on the national tax registration database.
File Missing Returns Early: Take advantage of the initial implementation phase (through June 30, 2027) to submit overdue returns and secure the maximum 70% fine reduction (paying only 30%).
Ensure Full Compliance and Accuracy: Exercise utmost care when declaring inactive periods. If tax liabilities are subsequently discovered by authorities, TINs will be reactivated, and full back-taxes, interest, and penalties will be enforced.
(Source: Government Draft Resolution 2026 on specific policies to resolve difficulties for taxpayers)